Bankruptcy and debt help in Milwaukee
Behind on bills? Let's look at your options, one calm step at a time.
Chapter 7, Chapter 13, or something else entirely. We explain it in plain words, put the fee in writing, and never judge how you got here.
Something urgent?
A date on the paper? Start there.
Tell us the date. Court deadlines go to the top of the list, with an attorney call back the same business day.
Prefer to type? Text (414) 555-0163, Monday to Saturday.
What you can count on, from the first call
- Free 45-minute consultation
- Flat fees in writing
- Evening and Saturday times
- Se habla español
- An attorney at every meeting
- Same-day call back for court dates
Start here
All options
Find your path
Pick what sounds most like you. These are starting points, not a diagnosis: the free consultation is where the real answer comes from.
Talk it through- Urgent help Foreclosure defense Read the court papers, find the deadlines, see what is still open. Read more
- Repayment plan Chapter 13 Spread missed mortgage payments over three to five years. Read more
- Other paths Loan modification Sometimes the lender will lower the payment. We compare it honestly. Read more
How it works
Five steps, and you're never guessing what comes next
Most people tell us the hardest part was making the first call. After that, it is a checklist and a team that answers the phone.
-
01
Free consultation
In person, by phone or by video. We listen first, then explain your options in plain words.
-
02
A plan and a fee in writing
The path that fits, what it costs, and what you can expect to keep.
-
03
Paperwork, with a checklist
Jasmine sends a simple list. You gather, we prepare every form.
-
04
Filing and the stay
The automatic stay starts the day we file, which stops most collection.
-
05
We stay with you
The trustee meeting, the hearings and the questions after. Same team, start to finish.
The means test looks back at your last six months of income
Your average income for the six full months before filing is compared with the Wisconsin median for your household size. A job loss or a slow season can change the answer, so timing matters.
Average your six monthsWhy people choose Daylight
Read all reviewsDana R.
Bay View · Chapter 7
"I put off calling for a year because I was embarrassed. Nobody made me feel that way. Renée explained Chapter 7 in plain words and told me what I could keep before I paid a cent."
Marcus and Leah T.
West Allis · Chapter 13
"We were three months behind on the house. Theo put Chapter 13 and a loan modification side by side for us. We chose the plan, and two years in we are still making it work."
Priya S.
Wauwatosa · Alternatives
"They told me not to file. My debts were smaller than I thought, and Hannah helped me settle two accounts instead. Honest people."
Luis G.
Milwaukee · Wage garnishment
"My next pay stub after filing still had the garnishment on it, which scared me. Jasmine called payroll that morning and the one after that was clean."
Reviews are from past clients and describe their own experience. Every case is different, and no result is guaranteed.
Small on purpose
Three attorneys and one very kind voice on the phone
You'll know who is handling your case, and you'll be able to reach them.
Meet the team-
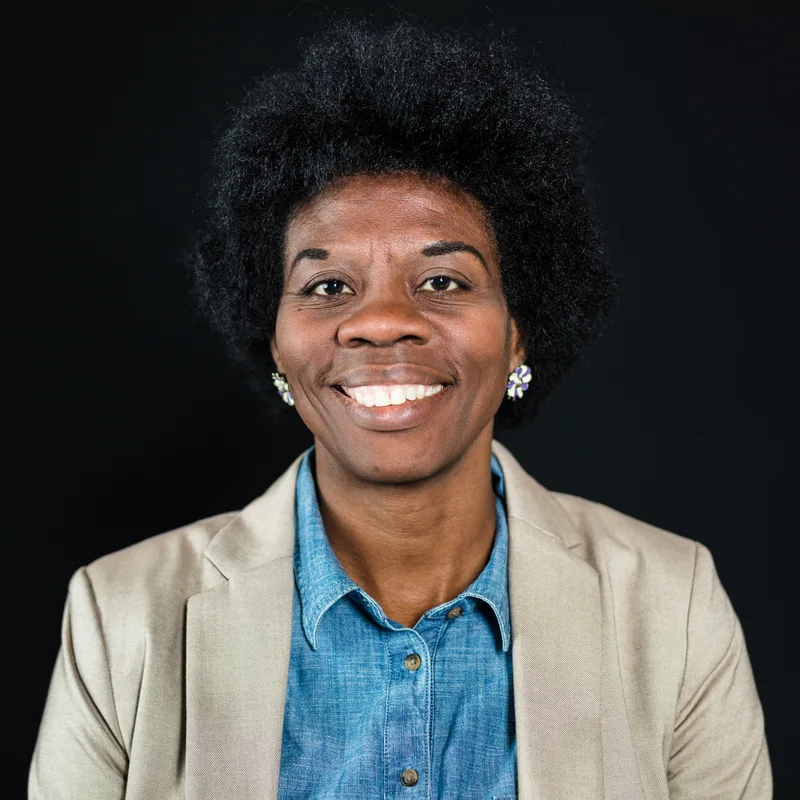
Renée Okafor
Founding attorney
-
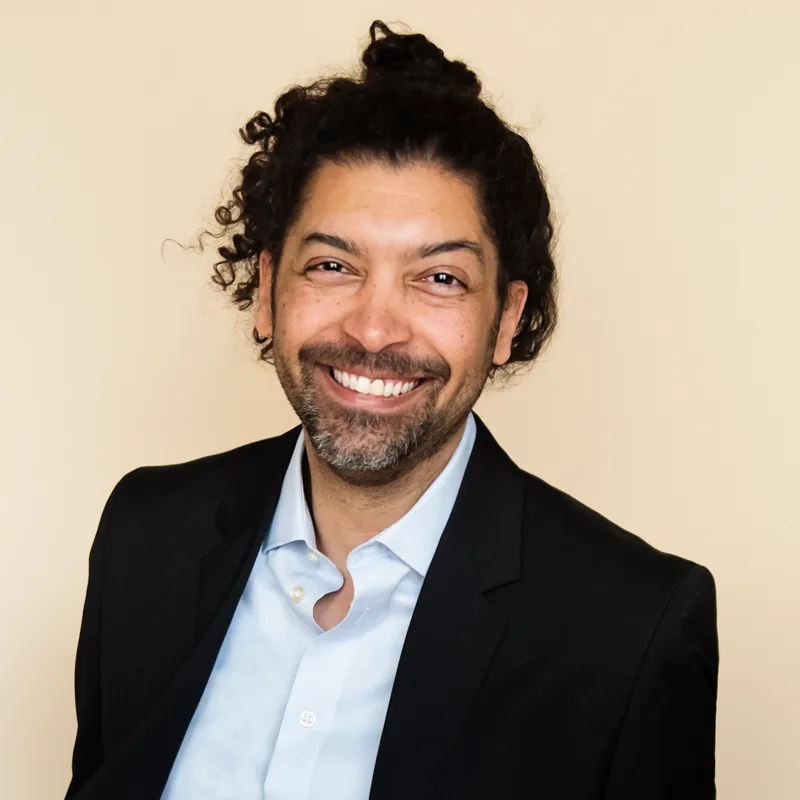
Theo Lindqvist
Attorney
-
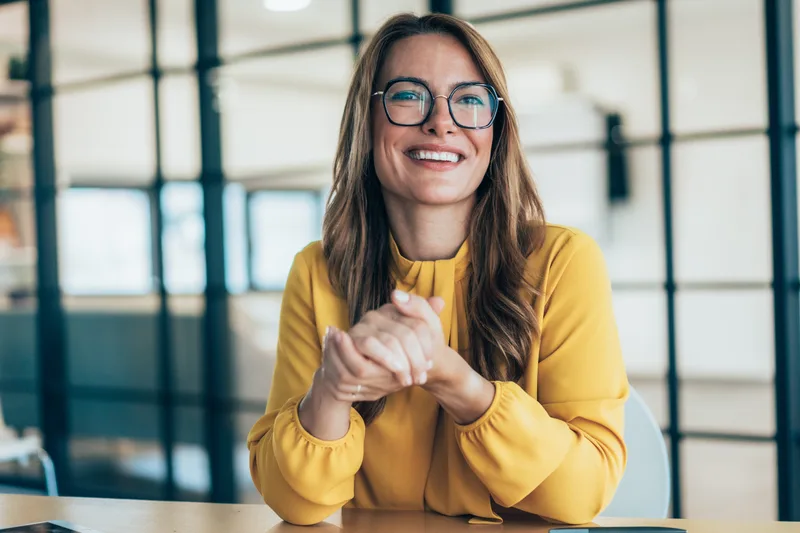
Hannah Brecht
Attorney
-
Jasmine Reyes
Client care lead
Frequently asked questions
Will you judge me for being in debt?
No. Most of the people we help got here through a job loss, medical bills, a divorce or a business that did not work out. Our job is to look at the numbers with you, not at you.
What is the difference between Chapter 7 and Chapter 13?
Chapter 7 is a fresh start that usually takes about four months and clears many unsecured debts. Chapter 13 is a three to five year repayment plan that can help you catch up on a house or car and keep property.
What is the means test?
It is how the law decides whether you can use Chapter 7. It first compares your average income from the last six months to the Wisconsin median for your household size. If you are above it, a second step looks at allowed expenses.
Will I lose my house?
It depends on how much equity you have and whether you are current on the mortgage. Exemptions protect a set amount of equity, and Chapter 13 can spread out missed payments. We check this before you file.
Does filing stop collection calls and lawsuits?
Filing starts the automatic stay, which generally stops most collection calls, lawsuits, garnishments and foreclosure sales while your case is open. There are some exceptions, such as support.
Can I pay over time?
Yes. For Chapter 7, you can pay in up to five monthly payments before we file. For Chapter 13, as little as $500 is due before filing, and the rest is paid through your plan as the court approves.
1 Timelines are typical ranges, not promises. Your case depends on your facts, the court's calendar and how quickly paperwork comes together.
2 Flat fees are starting points for typical cases and are confirmed in writing after the free consultation. Court filing fees are set by the court.
Free consultation
Ready to talk it through? It's free, and there's no judgement here.
A 45-minute consultation in our office, by phone or by video. You'll leave knowing your options, the likely cost and the next step, even if that step is not bankruptcy.